Mortgage rates ease late in the month as FHA gains share and refinance share slips to 16%
PLANO, Texas, Nov. 10, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its October 2026 Market Advantage mortgage data report, which found that adjustable-rate mortgage (ARM) share reached a new high even as rate-lock volume declined across every major loan category. Total rate-lock volume fell 19% month over month (MoM) and 38% year over year (YoY). Purchase volume declined 18% MoM and 17% YoY but still accounted for 84% of October locks, while refinance share fell to 16% of total production. ARMs represented 17% of total lock volume, the highest share in Market Advantage data going back to 2019.
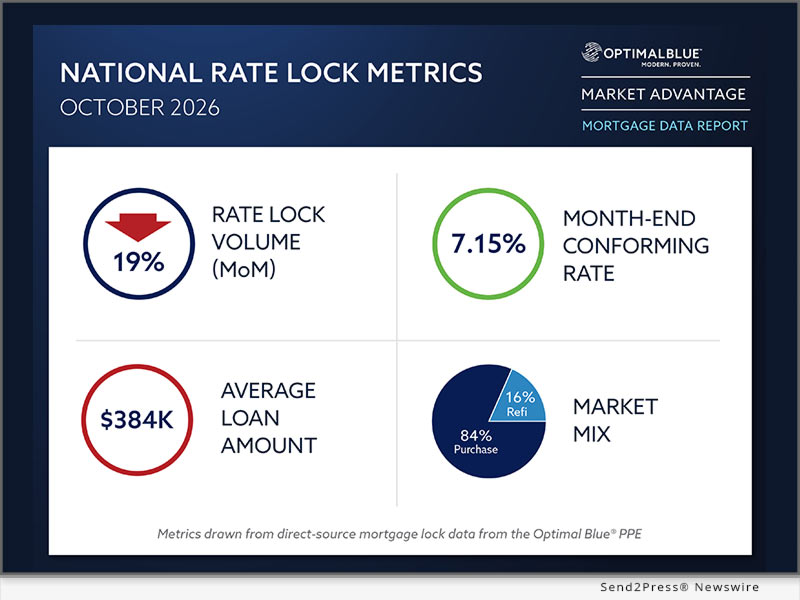
Image caption: Optimal Blue’s October 2026 Market Advantage mortgage data report.
Mortgage rates eased late in October but remained well above year-ago levels. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, ended October at 7.15%, down 24 basis points (bps) during the month but up 43 bps over the past three months and 99 bps YoY. The 30-year jumbo rate held at 7.36%, with Federal Housing Administration (FHA) loans at 7.00% and U.S. Department of Veterans Affairs (VA) loans at 6.76%. The 10-year Treasury finished October at 4.94%, down 35 bps during the month, while the spread between the 10-year Treasury and the OBMMI 30-year conforming fixed rate widened 11 bps to 221 bps.
“October’s data show how much affordability is shaping the purchase market,” said Brennan O’Connell, director of data solutions at Optimal Blue. “ARM share reached another high, FHA gained share and first-time buyers took a larger share across the major agency programs. For lenders, that means the opportunity is increasingly in helping borrowers find the product and payment structure that works for their circumstances.”
On the secondary side, best-efforts-to-mandatory spreads widened across all major products, with conventional 30-year spreads rising 15 bps to 41 bps. Lender hedges moved to higher coupons. The UM30 6.0, the 6.0% coupon for 30-year uniform mortgage-backed securities (MBS), became the most widely used hedging instrument at 57% of hedges, up from 44% in September. MBS execution declined to 43% of hedged loan sales, while the share of loans sold at the highest price tier rose to 80%. Mortgage servicing rights (MSRs) for conforming 30-year loans increased 2 bps to 1.41%, a 5.63 multiple, and the share of loans sold servicing retained fell to 53%.
“The jump in best-efforts-to-mandatory spreads shows investors are paying lenders more to take on interest rate risk. That makes best-efforts execution more expensive and a well-managed mandatory pipeline more valuable,” said Mike Vough, Optimal Blue’s senior vice president of corporate strategy. “Hedges moved quickly to the 6.0 coupon, but production is split between the 6.0 and 6.5, so lenders should confirm their hedges match where loans are slotting. With MSR values barely moving, more lenders also chose to release servicing.”
Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data and Virtual Economist forward-looking forecasts, include:
VOLUME TRENDS AND MARKET COMPOSITION
- Refi share slips: Refinances accounted for 16% of October production, down 125 bps MoM and nearly 21 percentage points YoY. Cash-out refinance volume fell 22% MoM and 44% YoY, while rate-and-term refinance volume declined 29% from September and 85% YoY.
- Purchase volume declines: Purchase lock volume fell 18% MoM and 17% YoY, accounting for 84% of total lock volume in October.
- Government lending gains share: Conforming share declined 9 bps MoM to 46%, while non-conforming share fell 174 bps to 22%. FHA share rose 153 bps to 20% of production, and VA share increased 29 bps to 11%. Compared with a year ago, conforming share was down nearly 7 percentage points and non-conforming share was up more than 5 percentage points. FHA share was up 219 bps YoY, while VA share was down 108 bps.
- Non-QM remains elevated: Non-qualified mortgage (non-QM) loans accounted for 12% of October production, down 24 bps MoM but up 195 bps over the past three months and 420 bps YoY. Investor and debt service coverage ratio (DSCR) loans represented 35% of non-QM activity, bank statement loans accounted for 32% and other expanded guideline programs made up the remaining 33%.
- ARMs set another high: ARMs accounted for 17% of total lock volume in October, up from 14% in September and the highest share in Market Advantage data going back to 2019.
- PUD share edges up: Single-family detached homes represented 64% of production, down 38 bps MoM. Planned unit developments (PUDs), a proxy for new-construction activity, increased 23 bps to 28% of volume and were up 136 bps YoY. Condominiums accounted for nearly 6% of production.
RATES AND PRICING
- 10-year Treasury rallies: The 10-year Treasury yield fell 35 bps MoM to 4.94% but remained 83 bps higher YoY. The spread between the 10-year Treasury and the OBMMI 30-year conforming fixed rate widened 11 bps during October to 221 bps.
- Conforming rate dips: The OBMMI 30-year conforming fixed rate fell 24 bps MoM to 7.15% but was up 99 bps YoY. The 30-year jumbo rate held at 7.36%, while FHA rates fell 10 bps to 7.00% and VA rates fell 33 bps to 6.76%.
- MSRs tick higher: MSRs for conforming 30-year loans increased 2 bps to 1.41%, a 5.63 multiple, while the average OBMMI 30-year conforming fixed rate rose 33 bps during the month.
- More loans sell at top price: The share of loans sold at the highest price tier increased 275 bps to 80% in October. Second-ranked executions increased 9 bps to 14%, third-ranked executions declined 54 bps to 3% and fourth-tier or lower executions declined 230 bps to 3%.
MARKET OUTLOOK
- Rates forecast to rise, then ease: The OBMMI 30-year conforming fixed rate is forecast at 7.30% over the next month and 7.39% over three months before easing to 7.24% over the next 12 months.
- Spread forecast to narrow slightly: The primary-secondary spread is forecast to narrow from 1.08% to 1.07% over the next month and to 1.06% over three months, holding at that level over the next 12 months.
CHANNEL AND EXECUTION
- Hedges move to the 6.0 coupon: The UM30 6.0 became the most widely used hedging instrument at 57% of hedges, up from 44% in September, while the UM30 5.5 fell to 30% and the UM30 6.5 accounted for 12%. By comparison, 27% of production priced into the 6.0 coupon and 24% into the 6.5 coupon.
- Best-efforts spreads widen: Best-efforts-to-mandatory spreads for conventional 30-year products increased 15 bps MoM to 41 bps. Government 30-year spreads increased 8 bps MoM to 18 bps. Conventional 15-year spreads increased 18 bps MoM to 58 bps.
- MBS share eases: The share of hedged loan sales delivered via MBS declined 355 bps to 43%. Cash execution increased 330 bps to 32%, with bulk execution at 22% and best-efforts at 2%.
- Spec-eligible share climbs: The share of a lender’s pipeline eligible for specified pool delivery rose to 80.7% from 80.3%. The largest increase came from loans with balances between $150,000 and $250,000, which rose from 19.89% to 20.22%. The largest decrease came from the $450,000 unpaid principal balance tier, which declined from 8.17% to 7.96%.
- Servicing retention falls: The share of loans sold servicing retained declined to 53% from 56% in September.
PRODUCT MIX AND BORROWER PROFILES
- First-time buyer share rises: First-time homebuyers accounted for 45% of conforming purchase locks, up 120 bps MoM and 266 bps YoY. First-time homebuyer share was 70% for FHA and 47% for VA.
- DTIs hold steady: Purchase debt-to-income (DTI) ratios were little changed in October, with conforming borrowers at 37.1%, FHA borrowers at 44.1% and VA borrowers at 43.8%. Conforming DTI was up 0.5 percentage points YoY.
- Cash-out credit scores soften: The average credit score across all locks nationwide was 729 in October. Purchase credit scores averaged 734, cash-out refinance scores fell 6 points MoM to 692 and rate-and-term refinance scores averaged 740. By program, conforming borrowers averaged 751, FHA borrowers 677 and VA borrowers 711. The average loan-to-value (LTV) ratio was 80.7%.
- Refi pull-through slides: Purchase pull-through declined 82 bps MoM to 81.4%, while refinance pull-through fell 615 bps MoM to 68.5%.
- Average loan amount declines: The average locked loan amount fell 3% from September to $384,000.
To view the full October 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.
Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Alexandra Kreuter to be added to the media list.
For more data-driven insights from Optimal Blue, clients are encouraged to register for the company’s 2027 Summit taking place Feb. 1 – 3 in Scottsdale, Arizona. Registration is open at Summit.OptimalBlue.com.
ABOUT THE MARKET ADVANTAGE DATA REPORT
Optimal Blue issues the Market Advantage mortgage data report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. The report also includes forward-looking rate and spread forecasts generated by Virtual Economist, an AI- and machine learning-powered forecasting tool built on public economic data and Optimal Blue’s proprietary lock volume data. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.
Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.
ABOUT OPTIMAL BLUE
Optimal Blue powers strategic performance across the mortgage capital markets ecosystem. As the industry’s only proven end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes optimize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue helps deliver measurable ROI, visit OptimalBlue.com.
MULTIMEDIA
Image link for media: https://www.Send2Press.com/300dpi/26-1110-s2p-opblue-300dpi.webp
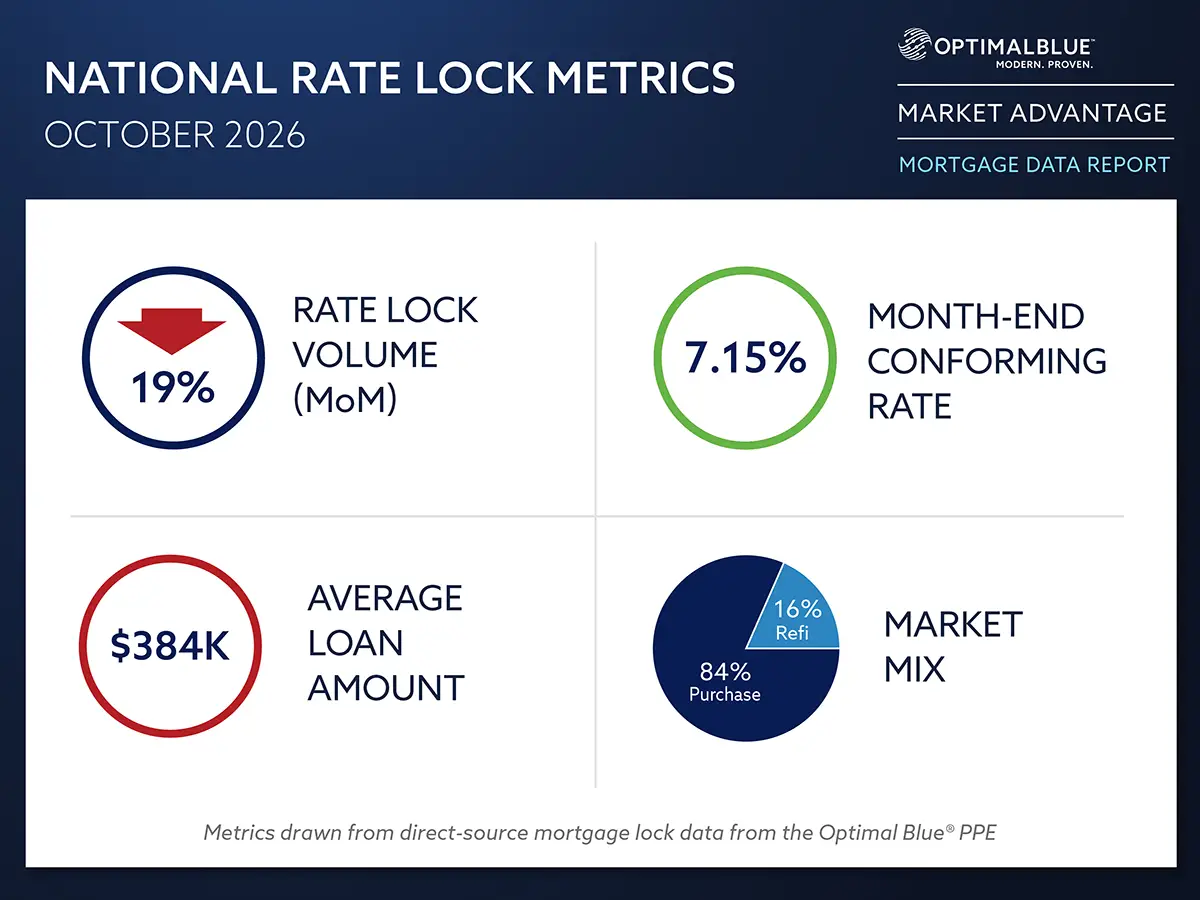
Image caption: Optimal Blue’s October 2026 Market Advantage mortgage data report.
NEWS SOURCE: Optimal Blue
This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire.
To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-arm-share-hits-new-high-as-october-lock-volume-falls-19/
Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: STORY ID: NEO139918 NEONET25C